
I was once persuaded by the moral indictments levelled by classical socialists. But the pro-socialist case I defended in the previous essay is only half the story. It would be disingenuous to pretend those arguments have not received serious and compelling replies.

The ideas advanced in that essay were not particularly new. One defining feature of socialism from our vantage point today is that it is no longer merely a hypothesis. Nearly a century has been devoted to its attempted (and successful) implementation.
The defining struggle of the 17th century was religious tolerance.
The 18th century fought for political liberalism and the end of caste privilege.
The 19th century abolished slavery.
The 20th century tested whether socialism could surpass capitalism.
The 21st century, it seems, will decide whether we become AI’s chattel.
Now that we are no longer in the 20th century, we can judge socialism both by its theory and by its fruits.
When I was first persuaded by socialism, the strongest arguments were the ethical ones: is there an element of private property norms and laws which enable exploitation? Are capitalism’s foundations intertwined with war, theft, and coercion which we now inherit, and do we wish to participate in that system? Can profit be justified along entirely mutually beneficial and voluntarist grounds, or is there an extractive element created by lopsided bargaining power? Do the rich get richer by producing cheaper, inferior goods to undercut their competition, while the poor remain poor by refusing to compromise their principles?
There is a whole genre of books that answers all of this and more, probably better than I ever could. Some of the big hitters in that field include The Road to Serfdom, The Gulag Archipelago, and Socialism, An Economic and Sociological Analysis. But these tend to run 800 pages or more, and what good am I if all I can do is tell you to read them yourself?
That said, this is not a book, so I will be brief.
I will use socialism in its classical sense: the abolition or severe restriction of private ownership of the means of production. It was generally inward-looking and national in scope. Lenin later distinguished socialism within a single country from the broader project of international communism, which Marx had expected to emerge from a global worker revolution that never materialized. That outward-looking and aggressively expansionist version of socialism is irrelevant to the discussion here.
I want to breeze through 3 quick pillars to keep this accessible.
The labour theory of value does not appear to be a descriptively accurate account of how markets actually work, and has a couple glaring issues
The rectification of historical injustices is politically intractable, and the classical liberals put forward a better solution
The calculation problem makes weighing trade-offs increasingly difficult, and 100 years later the criticisms of it (defenses of socialism) remain extremely weak and unpersuasive
Labour theory of value problems
The labour theory of value is, at first glance, a plausible theory of profit. But it does not offer a similarly persuasive theory of losses, which seems like a fairly large omission.
If profit is explained as the owner of capital using bargaining power to skim off part of labour’s product, then what exactly is happening when the firm loses money? Is the capitalist now being exploited by his own employees? If a company can post profits one month and losses the next, does the exploitative structure vanish seasonally and then return with the weather?
If taken seriously, this would require us to push our analysis back and further develop a new theory of when and where exploitation reaches a peak and then subsides, presumably requiring another socioeconomic law of nature to be invoked and explained.
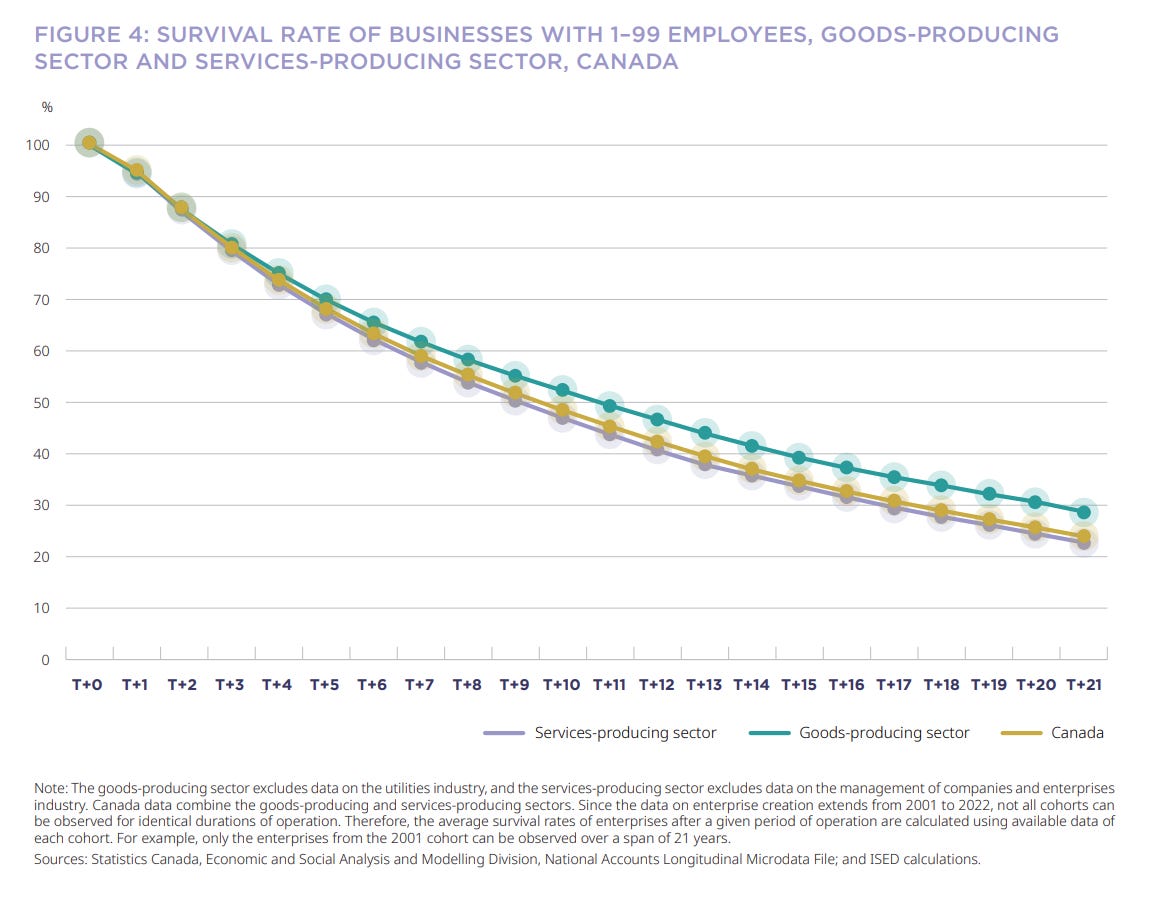
This seems like a remarkable flaw in the framework. Empirical work by the Canadian government suggests that roughly 40% of businesses fail within 5 years, and that number rises to 80% within 20 years. Are we really meant to believe that most business owners simply failed to exploit their workers hard enough, and were instead outmaneuvered by the bargaining genius of their fry cooks? Or do we perhaps need a different conceptual scheme?
The labour theory of value also struggled with the old water-diamond paradox. Water is necessary for life. Diamonds are mostly vanity. Why, then, is the latter often worth more?
Smith and Marx were aware of the paradox and attempted to resolve it by distinguishing between "value in use" and "value in exchange." Water has high use value, diamonds high exchange value. But drawing that distinction doesn't actually solve the paradox, it's just a restatement of the problem. We need an explanation of why the exchange values diverge the way they do. Neither Smith nor Marx had a mechanism that could explain why diamonds command higher exchange value than water.
The alternative economic theory that finally solved many of these problems was, in part, a remarkably humble capitulation: value is subjective.
Economics was turning out not to be the physics-like science Marx had hoped it would become. Where Marx aspired to establish uniform laws based on statistical averages and quantize human socioeconomic relations, the subjective theory of value forced economists to admit that the amount of human behaviour and interior mental life they would need to excise from the analysis would actually make the theory less scientific rather than more. Our inconsistencies, preferences and whims turn out to be essential for describing how we actually behave. This was not a defeat of wishy-washy charlatans over the genius mathematicians, but a realization that to accurately describe human exchange we needed to do so from a human-eye view.
This gives us a shockingly easy answer to why profit, losses, and trade happen at all. You love chocolate and I like vanilla. You find the book I wrote more valuable than the $15 in your pocket, while I value your $15 more preferable than a copy of my book. We do a trade and both profit. Turns out this emperor-wears-no-clothes approach to exchange works far better than any elaborate exploitation equation.
Losses occur when someone speculates wrongly about what others value. I write a book and hope to sell it for $15. Perhaps nobody wants it. Perhaps they would only pay $2. In that case I misjudged my fellow man’s preferences and lose money. I have to sell at a severe discount or even a loss.
It is really quite funny that “value is subjective” turned out to be the more comprehensive and accurate insight. We should not hold Marx’s ambitions against him though. He lived at a time when chemistry, mechanics, and mathematical formalization were conquering the world. It is easy to see why he wanted economics to follow suit. But in this case the variable he was tempted to treat as noise (human preferences) turned out to be almost the whole game. It was like trying to solve flight by omitting drag.
Marginalism then solved the water-diamond paradox cleanly. We do not compare all water to all diamonds in some Platonic sense, or care how much labour went into procuring it. We compare the diamond we are looking at with the cup of water we would probably go get.
Böhm-Bawerk, one of the early marginalists, took Marx’s analysis seriously and noted something Marx does not seem to have fully wrestled with: time.
A dollar today is worth more than a dollar tomorrow because it can be put to use immediately. That capacity to exert control over resources in the present is valuable in itself. The entrepreneur advances wages now in exchange for uncertain revenues later. Many workers, quite sensibly, prefer a guaranteed paycheque every two weeks to a speculative claim on a risky and delayed upside.
Take a piano store. Each piano might sell for nearly $100,000, but only one may move every couple of years. The owner is willing to bear that uncertainty. Many employees prefer not to. They would rather take steady wages and let someone else shoulder the risk. The exchange benefits both sides. Once you understand that, profit and loss (and the whole entrepreneur–labourer relationship itself) become two sides of the same coin, rather than some quantum-superposition backflip where surplus labour exploitation appears and disappears depending on the season.
The standard defence from more sophisticated Marxists is that this objection misses Marx’s level of analysis. He wasn’t describing what happens inside any individual firm. He was making a claim about the economy as a whole: what we would today call macroeconomics. He argued that in aggregate the total surplus extracted from workers across the entire system equals the total profit. The individual firm can win or lose; the class relationship is what matters in aggregate. We must always consider the “capitalist superstructure” as such, rather than specifics.
After Marx offers this, in the theory laden parts at the beginning of Capital vol. 1, he proceeds to spend the entire back half of the book doing case studies on actual firms and workers' conditions. But firm-level evidence only counts when it confirms the theory. Heart wrenching tales of children being denied a bite of food while working in the coal mines abound. Contradictory cases are dismissed as ideologically motivated. Workers doing well and rising into a middle class is not a real fact, just sycophantic bourgeoisie economists defending their class interests. The idea that a poor person/ worker could disagree with Marx is defined away. His historical narrative is entirely unfalsifiable due to the role “class consciousness” plays in shielding itself from criticism.
This is a serious problem for a theory that presents itself as scientific, and comes with its own set of other serious problems. Modern economics is deeply skeptical of macro claims that cannot be given what are called micro-foundations. If the picture does not make sense at the level of its parts (firms or people), it does not suddenly become coherent when we zoom out and look only at the whole. This is like the “God of gaps” of early macro, where people would just posit shit due to “psychological laws” or “multiplier effects.” Pointing to aggregate patterns while leaving the actual mechanism unexplained is hardly a solution, but a promissory note that is never cashed out.
As for the broader project of dialectical materialism, this is just untestable and irrefutable pseudoscience. Popper has seemingly won the hearts and minds of scientists everywhere. A willingness to brush up against falsification, or, at least, the politeness to pretend your field is doing so, is now seen as something a theory should always aspire to; not protect itself from.
Insider baseball: It is worth noting that Marx only ever published Volume I of Capital in his lifetime. Volumes II and III (the ones Marxists sometimes invoke to resolve the transformation problem) were unfinished manuscripts edited and published posthumously by Engels. Within Marxist circles this has produced two incompatible traditions: those who follow Volume I, where labour alone determines value and exploitation is structural and unavoidable, and those who follow the later volumes, where time and circumstance are also acknowledged as contributors to value. These two positions are not easily reconciled. If time and circumstance matter then surplus value is no longer the only explanation for profit, and the exploitation claim loses much of its force.
The subjectivist and marginalist framework doesn’t need a 5000 year meta-history of class relations and a power imbalance baked into every transaction. It only needs people at different stages of life, with different tolerances for risk and different time horizons, trading across those differences voluntarily. Workers prefer a guaranteed wage today over a speculative share of uncertain future revenues. Entrepreneurs prefer to bear that uncertainty in exchange for the potential upside. This is likely a description of almost every employment relationship you have ever seen or been part of.
In the philosophy of science, the Principle of Parsimony says that among competing explanations, we should prefer the one that introduces the fewest additional assumptions or auxiliary hypotheses, so long as it explains the same facts. For the same reason we no longer invoke epicycles or divine intervention to explain the motion of the planets, we don’t need to invoke exploitation, socially necessary labour time, or the rest of the Marxian apparatus to explain why wage earners receive steady pay while owners sometimes earn large profits or (more often) go bankrupt.
The rectification (historical injustices) problem
I have already written at length about rectification in my essay on the European Wars of Religion, so I will summarize.

The socialists and anarchists are largely correct about the facts of history. The foundations of capitalism are soaked in coercion, theft, and conquest. But having the correct diagnosis is different from procuring an efficient remedy.
The classical liberals learned something from the wars of religion that the socialists did not: conflict persisted not because it was irrational, but because it was morally rational on both sides. Each act of retribution appeared justified as restoration. Each attempt to settle the ledger created a fresh grievance and a new imbalance to be corrected. The historical rectification agenda is structurally endless, and never allows for stability within the market.
The wars ended not because Europe achieved theological or ethical agreement, but because it exhausted itself and reluctantly conceded that politics could not settle ultimate historical debts without destroying the society trying to settle them.
That lesson generalizes. Liberal tolerance is not a grand theory of justice. It is a technology for preventing a society from tearing itself apart over competing claims of justice. The case for applying that lesson to economic history is not that the ledger is balanced, but that no one has ever successfully balanced it, and attempts to do so are usually catastrophic.
Rather than trying to perpetually balance the scales of every injustice along every conceivable intersectional line or coalition, the classical liberals said: “Look, we’ve tried this for 200 years and it never works. The tit-for-tat cycle of retribution only creates an unending claim for further retribution. The scales will never balance so long as we keep thumbing them to correct the previous attempt. Let’s just all agree to treat each other as equals from this day forth, so we can at least stop perpetuating new injustices.”
Settling for equality going forward—ceasing future injustices, enforcing equal standing under the law—is unsatisfying in exactly the way the Peace of Westphalia was unsatisfying. It still leaves past wrongs unresolved. But it is the only settlement that has ever actually worked, and I am skeptical whenever someone says “Just one more redistribution and we will be able to move on…”
The economic calculation problem (ECP)
(I’m throwing Hayek’s knowledge problem in here too)
This is usually the point at which socialists begin to feel there may be a real difficulty with the project. One of the most prominent socialist theorists of the 20th century once remarked that the author who first articulated the calculation problem deserved a statue in the socialist hall of fame for identifying the last theoretical obstacle socialism needed to solve. Unfortunately, checking in on the socialist theorists now over a hundred years later, they never did manage to solve the problem.
The premise of the economic calculation problem is simple: you need private property in order to have markets. And you need markets in order to have prices.
If the government owned the entire apparatus of production and simply distributed goods for consumption, we would not really own anything. That is, in a sense, the promise of socialism: no ownership, no inequality, and the entire structure of production centrally coordinated and distributed according to need.
The problem is that without people owning things and trading them against their own subjective values, there is no market and therefore no process for discovering prices.
It is worth pausing for a moment on what I mean by “discovering” prices. They are not imposed by sellers. They emerge from repeated transactions over time.
Suppose I want to sell my book for $200 because I love it and it is worth that much to me. The problem is that almost nobody else agrees. At $50 perhaps ten people buy it. At $40 maybe thirty copies sell. At $30 perhaps seventy. At $20 around 130 readers appear. Eventually I discover that around $15 the book reaches roughly 200 buyers — a price that balances how much people value the book with how many are willing to buy it.
This of course also gives us the standard supply and demand graph you have probably seen a thousand times in your life.
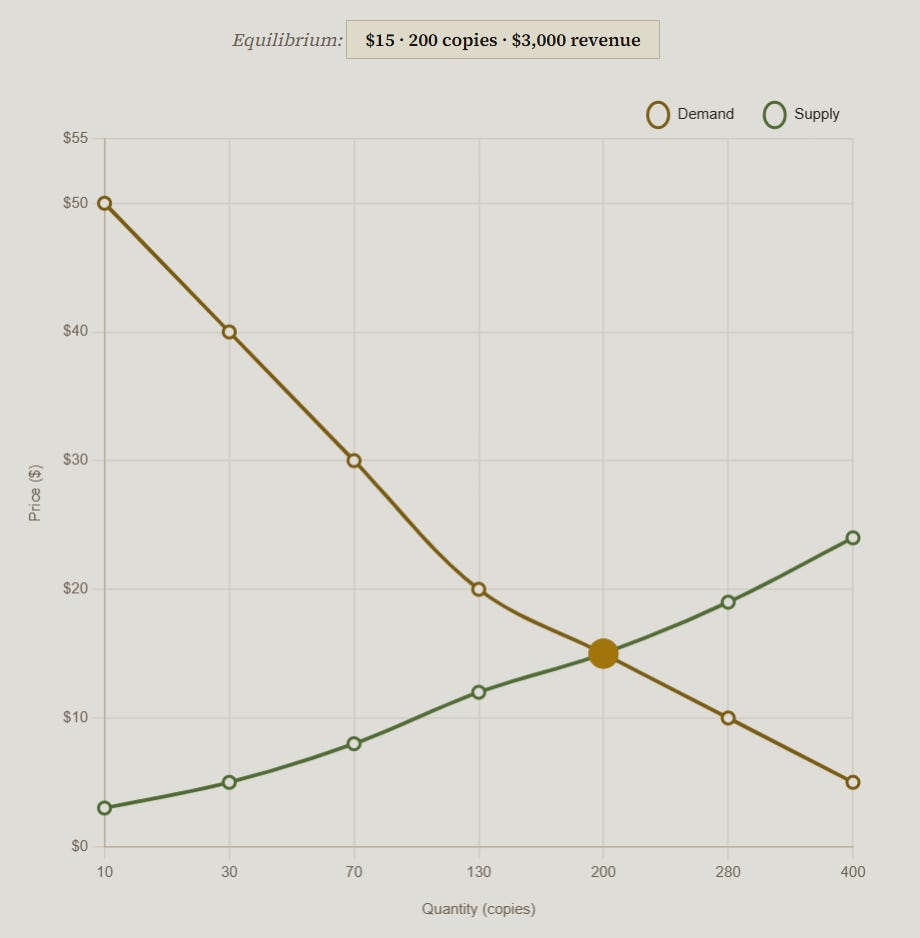
Through trial and error (or simply by observing what others are charging) the seller is pushed toward the price that attracts the most buyers while still maximizing revenue, and the market clears where those forces intersect.
Prices are therefore not arbitrary numbers or the product of the seller’s fiat. They are signals generated by millions of decentralized decisions as consumer preferences collide with scarcity.
These signals do something extremely important: they allow producers to compare alternative methods of production.
Suppose a Canadian grocer wants to bring pineapples north during the winter from California. Should they be flown, trucked, or shipped by rail? Under capitalism, the answer is boring: compare the costs. Whichever method gets the fruit there cheaply enough to cover its costs and still meet consumer demand wins.
Under socialism, where the capital goods are collectively owned and no market prices emerge for them, that arithmetic breaks down. The planner may know that planes are faster than trucks, or that rail is more fuel-efficient over long distances, but he cannot reduce these alternatives to a common denominator shaped by real market exchange. He cannot know whether speed is worth the extra fuel, whether labour is better used elsewhere, or whether those rail lines are urgently needed by another industry willing to bid them away.
The planner can have all the engineering and physics facts. What he lacks is a price system that lets him compare trade-offs across competing uses; trade-offs ultimately determined by subjective preferences rather than brute physical facts.
That is the calculation problem.
The issue is not that planners are stupid or just need supercomputer AIs to sift through all the data. It is that cost-effective allocation in a complex economy requires more than technical knowledge. It first requires the creation of prices that emerge when individuals weigh their wants against the available goods, and second, a way to compare alternative methods of producing those goods across millions of changing uses and possibilities. Market prices make those comparisons possible in a way central planning has remained incapable of replicating.
In their book “The Turning Point” Soviet economists Nikolai Shmelev and Vladimir Popov recalled that they had to look outward to the surrounding capitalist economies in order to approximate what things ought to cost inside the USSR. In practice, even Soviet socialism relied on capitalist markets as its measuring rod.
The critique then boils down to this: economic calculation—comparing alternative uses of resources through prices—is impossible under radical, abolish all private property-type socialism. Prices emerge from trade, and trade requires private property. Without that process, the values of individuals never make contact with the structure of production. The planner is left, as Mises put it, groping in the dark.
Socialists attempted to answer this critique through proposals like “market socialism,” or by suggesting that the state could gradually purchase all private property rather than abolish it overnight. But the problem never really disappears.
In practice, socialist economies often begin by inheriting the price structure created under capitalism. For a time those prices can serve as a rough guide. But as years pass and production decisions are made without real market exchange, those prices drift further and further away from the underlying realities of material scarcity in the economy, consumer preferences, and their ongoing interaction.
Eventually the signals become meaningless. The planner still has numbers, but they no longer correspond to the relevant opportunity costs and trade-offs they once represented.
When circumstances inevitably change the system has no reliable way to adapt. If a mine collapses on the other side of the world and aluminum suddenly becomes scarce, market prices immediately transmit that information throughout the production chain. Firms do not need to know what happened. They simply observe the price of aluminum rising and respond by slowing production, substituting materials, or raising their own prices. The scarcity propagates through the entire production chain until consumers ultimately buy fewer aluminum-intensive goods.
A central planner has no equivalent mechanism. The shortage must be reported upward, interpreted by the planner, and translated into new production quotas—without any reliable way to measure which adjustments (substituting, economizing, allowing shortages) are actually most efficient—and then sent all the way back down the production line. Whether socialism arrives gradually or by revolution does nothing to solve the planner’s problem.
What was once celebrated as the final piece socialists needed to resolve to bring about scientific socialism has instead stopped the entire project in its tracks. Modern socialists rarely mention the abolition of private property anymore.
The modern socialist will sometimes gesture at computing power or AI as the deus ex machina that finally solves the calculation problem. “If only we had enough processing power, we could simulate the market and plan rationally.” But this misunderstands a portion of what the critique was actually saying. The problem was never a shortage of computation or the planner’s intelligence. It was that preferences are not data points waiting to be harvested, rather, they are only ever created through the act of choosing under real constraints. That Darwinian selection process the bookseller went through earlier is what gives rise to the price. It did not exist in the abstract before that process actually happened, where consumer preferences were tried and tested against the material conditions.
The Hail Mary of an AI agent that "chooses for you" in a planned economy is only a proxy for your preferences, not your preferences themselves. It substitutes a model of what you want for the actual discovery process of finding out what you want when forced to trade it against something else. Even a perfect computer faces the same fundamental problem: it cannot receive signals that the market itself would have generated, because those signals do not come into existence until the transaction has occurred. No AI can solve this unless humans agree to never change their minds, never act on a whim, and never decide that despite a lifetime of drinking Pepsi, a Coke sounds good right now.
Modern socialism rarely calls for abolishing private property outright. Instead it proposes a tamer program of keeping markets, but declaring certain politically salient goods rights, capping some prices, putting floors on others, and redistributing more. In a future essay I’ll examine if and how that more moderate project avoids the problems discussed here.
I'm not even a socialist anymore and these objections are extremely weak. (Note I haven't read the the thing, so sorry if you already anticipated this): the labour theory of value and whether historical injustices are "rectified" or not aren't relevant to socialism. The ECP is only relevant to non-marks socialism.
This is a good article, but I have thoughts on this section -
"Take a piano store. Each piano might sell for nearly $100,000, but only one may move every couple of years. The owner is willing to bear that uncertainty. The employees generally are not. They would rather take steady wages and let someone else shoulder the risk. The exchange benefits both sides."
We can't know that, because the employees likely have no capital. They may well prefer to take the risk themselves if they found themselves in the position of having access to sufficient capital to be able to set up their own piano store, to use your example.
The question then becomes do people exchange labour for money because they prefer this, or because they have to? I think that for most people it's more the latter than the former, hence the perennial popularity of starting one's own business as an aspiration of the working and middle classes.
What do you think?